
US stocks suffered a sharp selloff, with the S&P 500 dropping 1.21% and the Nasdaq falling 2.9%, as markets in Asia and Europe followed with broad declines of their own, in a session that Deutsche Bank strategist Jim Reid described as the collision of “the wobbles of recent weeks” all hitting at once.
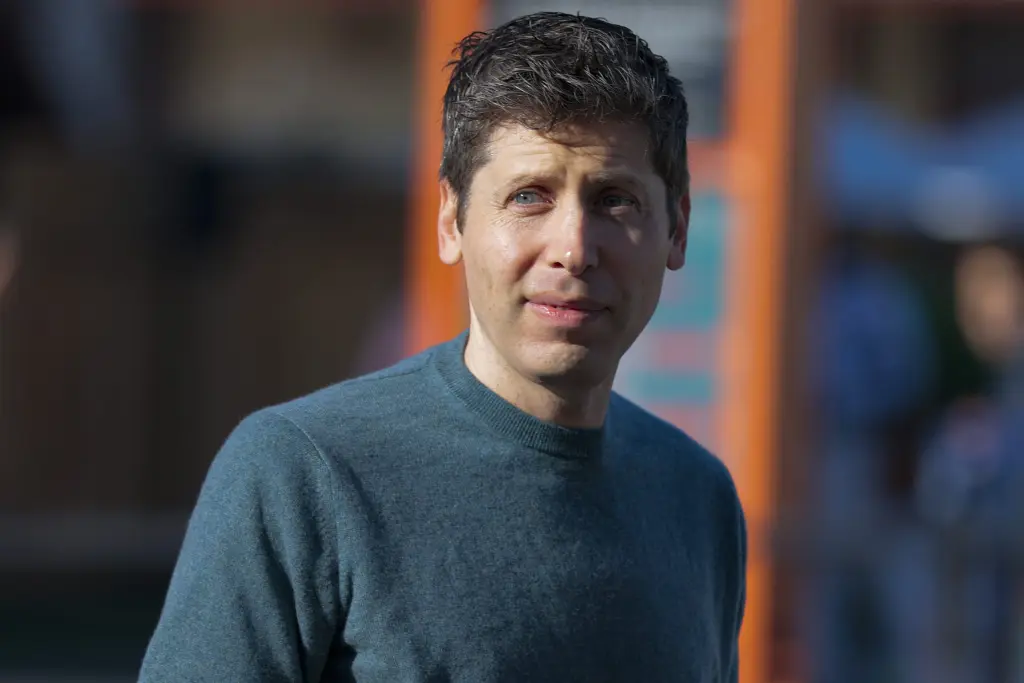
Anxiety over AI valuations drove much of the tech-sector pain, after reports emerged that OpenAI had been pushed by private equity investors to lower the valuation target for its latest fundraising round, from $1.4 trillion down to $1.25 trillion. AI cloud provider CoreWeave fell more than 10% on the day and is now down 22% for the year.
Oil added to the pressure, climbing to $114 a barrel after the Financial Times reported that President Trump’s envoy to the United Nations said the US was prepared to continue confronting Iran for at least another year, reinforcing expectations of a prolonged and costly regional standoff.
France contributed its own source of strain, with yields on the country's 10-year bond spiking to a fresh high of 5.1% before easing slightly back to 5.05%, a move that reflected deepening investor unease over the country's fiscal trajectory.
The combination of fading confidence in AI infrastructure spending, rising energy costs tied to geopolitical risk, and renewed sovereign debt concerns in Europe gave investors three distinct reasons to retreat simultaneously, rather than a single dominant narrative driving the selloff.
With all three pressure points, AI valuations, oil-linked geopolitical risk, and European debt, still unresolved, markets are likely to remain vulnerable to further swings depending on which of the three threads moves next.